They want certainty. They want flexibility. They want protection for their family, but they also want their capital positioned intelligently in a world of inflation, volatility, and constant regulatory change. Traditional insurance protects against risk.
Traditional investments pursue growth.
Indexed Universal Life, when structured correctly, can bridge both. At its core, it is permanent life insurance with a cash value component linked to a market index. Rather than being directly invested in equities, the policy credits interest based on index performance, with a floor (often 0%), so that in years when the index falls no loss is credited, although policy charges still reduce the account value.
That structure matters. It allows long-term capital to compound in a controlled environment. It provides life cover while the policy stays in force. It can offer tax-efficient accumulation in some jurisdictions, depending on residence. And, when designed correctly, it can provide flexible access to capital later in life.
It is either engineered correctly, or it isn’t. The difference lies in funding design, policy structure, jurisdiction, and how it integrates into a wider financial plan. Used incorrectly, it can underperform expectations. Used strategically, it can support:

Long-term wealth accumulation.
Supplemental retirement income planning.
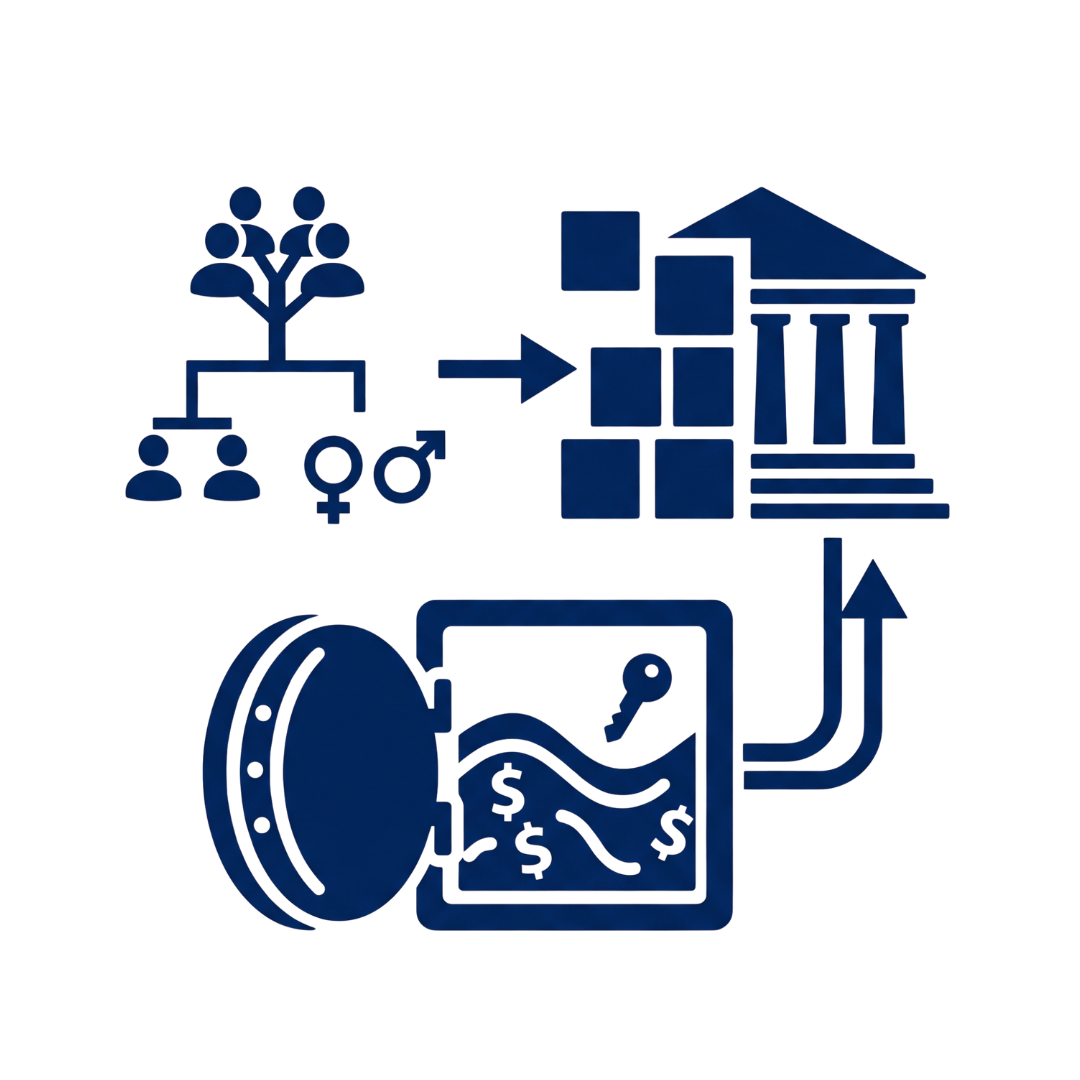
Estate and succession structuring.
Liquidity provision for complex estates.

Risk diversification outside traditional portfolios.
Cross-border tax positioning.
Cross-border wealth planning for global families and entrepreneurs.
Insurance strategies tailored to international needs and objectives.
Advice given only through Neba Private Clients after a full fact-find.
Succession and estate structuring across jurisdictions.
Retirement and pension planning for expatriates and executives.
Ongoing support through major life transitions.

My focus is never on the product itself. It is on the architecture behind it. For internationally mobile families, business owners, and those navigating multi-jurisdictional tax environments, Indexed Universal Life can address some structural challenges that traditional portfolios may not. It is not a replacement for investments.
It is not a short-term strategy. And it is not suitable for everyone. But when aligned with the right objectives, designed with discipline, and integrated into a broader wealth strategy, it can be a useful planning tool.
Working with a regulated financial adviser helps make sure any policy fits your wider plan. ensures your comprehensive wealth strategy is built entirely around your personal objectives, free from institutional product restrictions.
The value is not in the illustration.The value is in the structure.
Educational information only – not advice. IUL involves policy charges, caps and surrender penalties; credited growth is not guaranteed above the floor, the cash value can fall because of charges, and tax treatment depends on residence and may change. Any advice is given only by Neba Private Clients after a full fact-find.
Educational only, not advice. James Spence is a Partner, Family Office and Private Client Adviser, with Neba Private Clients. This website is published for general educational information only. Nothing on it is an advertisement, an offer, a recommendation or personal financial, tax or legal advice, and it should not be relied on as such. Tax rules depend on individual circumstances and may change. The value of investments can fall as well as rise. Case studies are hypothetical or anonymised composites and do not describe real clients or predict outcomes. Advice is only given after a full fact-find, under a signed client agreement with Neba Private Clients. Not directed at persons in any jurisdiction where its publication would be unlawful, including the United Kingdom.
All rights reserved ©2026